US Midterms and Israeli Elections Signal Policy Shifts and Volatility Across Six Sectors
Simultaneous Electoral Pivots Drive High Severity Market Uncertainty
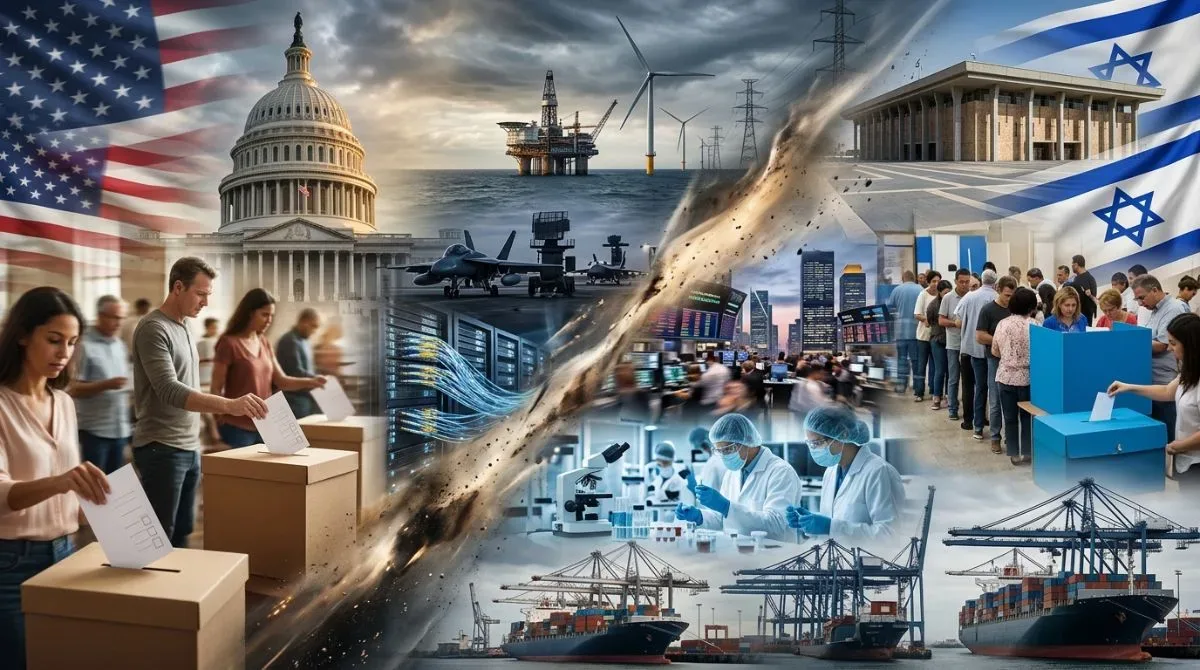
Today, October 27, 2026, global financial markets face a rare alignment of geopolitical uncertainty as US midterm election campaigns reach their climax alongside active parliamentary voting in Israel. According to SaPEX NEXUS's Geo Risk AI model, this dual political event registers a high severity rating with an event probability score of one hundred percent. The model indicates that simultaneous leadership transitions and legislative balance shifts inherently create structural friction in international asset pricing, driving heightened risk aversion across global trading desks.
Data recorded today by SaPEX NEXUS's Prediction Arena tracker shows Democrats holding a slight lead in US polling metrics, while Israeli citizens cast ballots in a highly competitive national contest. The convergence of these two high-stakes votes introduces multi-layered policy unpredictability across six primary industries explicitly identified by the platform: Finance, Technology, Energy, Defense, Healthcare, and Trade. Market participants across global exchanges are forced to price in sudden shifts in domestic regulation, spending priorities, foreign policy, and international trade relations concurrently.
When major democratic economies experience overlapping electoral cycles, financial markets routinely react with elevated volatility across fixed income, equity, and foreign exchange markets. SaPEX NEXUS's Geo Risk AI model highlights that major political transitions force institutional portfolio managers to recalibrate risk-free rate assumptions, equity risk premiums, and hurdle rates across diverse asset classes. As exit polls and initial precinct returns begin to surface over the coming hours, immediate liquidity flows are expected to reflect institutional caution, risk reduction, and flight to traditional safe-haven assets rather than strong directional conviction.
Near Term Volatility and Sector Vulnerabilities
The three-month outlook published today by SaPEX NEXUS's Horizon Forecasting module underscores immediate risks of legislative gridlock within the United States federal government. If the projected slight Democratic lead results in a divided legislative branch, the passage of expansive fiscal packages, sweeping tax modifications, or major regulatory reforms could slow dramatically. Corporate earnings forecasts in highly regulated sectors such as Technology and Healthcare often suffer from diminished forward visibility during such legislative impasses, prompting institutional capital to temporarily pull back from aggressive capital deployments.
Simultaneously, the active voting process in Israel introduces immediate foreign policy and currency dynamics into broader international markets. SaPEX NEXUS's Market Impact Monitor indicates that rapid shifts in Israeli executive leadership can spark immediate diplomatic adjustments across the Middle East. Regional defense equities, sovereign bond spreads, and energy infrastructure assets typically experience real-time repricing as strategic foreign policy stances are reassessed by international counterparties and global rating agencies.
Currency and commodity markets remain especially sensitive during the early post-election window. Detailed analysis from SaPEX NEXUS's Sector Analytics system indicates that regional currency fluctuations, alongside potential shifts in spot crude oil and natural gas pricing, frequently follow contested or high-stakes Israeli elections. Market participants operating in foreign exchange desks and energy derivative markets must prepare for potential spikes in implied volatility and widened bid-ask spreads while official election counts are verified by regulatory authorities.
Medium Term Realignment Across Fiscal and Defense Policies
Looking ahead to the six-month horizon, SaPEX NEXUS's Horizon Forecasting module details how initial electoral outcomes transition into concrete, formalized policy frameworks. In the United States, newly seated lawmakers will officially assume office and begin defining regulatory agendas, international trade stances, and national fiscal priorities. Capital-intensive industries like Energy and Trade face distinct operational shifts depending on which party controls key Congressional committees responsible for statutory oversight, environmental standards, and federal budget allocations.
For Israel, the six-month period following national elections primarily centers on complex coalition building and cabinet appointments. Data from SaPEX NEXUS's Risk Intelligence engine highlights that the duration and stability of coalition negotiations directly influence international investor confidence and domestic economic sentiment. A prolonged coalition formation process can temporarily delay strategic bilateral agreements, foreign direct investment inflows, and major infrastructure projects, whereas a swift government resolution tends to restore cross-border capital flows into domestic technology ventures and growth sectors.
Furthermore, global trade networks and multinational corporate leadership will begin adjusting their long-term supply chain strategies to match the updated geopolitical baseline. SaPEX NEXUS's Sector Analytics system notes that international trade relations are heavily calibrated against political continuity and predictable regulatory enforcement. When dual elections of this magnitude alter key diplomatic vectors, corporate treasury departments tend to delay major foreign direct investment and cross-border expansion plans until clear bilateral regulatory directives become fully established.
Twelve Month Macroeconomic Trajectories and Structural Shifts
By the twelve-month mark, the comprehensive macroeconomic footprint of today's elections will be largely established and integrated into broader market valuations, according to SaPEX NEXUS's Macro Planning framework. In the United States, the newly established legislative environment will exert direct, measurable influence on national inflation trajectories, baseline central bank interest rate expectations, and broader gross domestic product growth forecasts. Major fiscal policy recalibrations in Washington invariably spill over into sovereign debt yields, international credit markets, and benchmark equity indexes worldwide.
Concurrently, the one-year evaluation from SaPEX NEXUS's Geo Risk AI model points to solidified long-term strategies in Israeli defense spending, cyber-security initiatives, and energy policy. Strategic defense procurement budgets and long-range natural gas export agreements depend heavily on the strategic orientation and foreign policy posture of the governing cabinet. Institutional capital allocations to regional defense contractors, infrastructure debt instruments, and public equities are heavily shaped by the verified stability and policy consistency of the governing coalition.
Over this extended twelve-month timeframe, systemic risk premiums typically begin to normalize across global asset classes as campaign rhetoric gives way to practical legislative compromises. Analysis from SaPEX NEXUS's Prediction Arena tracker suggests that clear legislative trajectories reduce policy uncertainty, allowing equity valuations across Finance, Technology, and Energy to re-anchor onto fundamental corporate metrics, balance sheet strength, and earnings growth rather than political headlines.
Long Term Strategic Considerations for Global Portfolios
Over the multi-year horizon, the lasting structural effects of today's dual election events will reshape global economic competitiveness, trade alliances, and strategic geopolitical alignments. SaPEX NEXUS's Risk Intelligence engine evaluates these long-term developments as primary catalysts for structural shifts in market dynamics and multi-asset risk pricing. The ongoing interplay between US legislative directions and Middle Eastern diplomatic stability establishes the broad operational parameters for global energy security, cross-border technology transfers, national security spending, and international financial regulatory standards.
For institutional portfolio managers, wealth advisors, and active market traders, navigating these multi-year structural trends requires continuous reliance on objective, real-time quantitative data rather than speculative political commentary. SaPEX NEXUS's Market Impact Monitor emphasizes that long-term strategic asset allocation models must account for structural modifications in tax structures, trade tariffs, and regulatory oversight across all six impacted market sectors to preserve risk-adjusted returns over extended investment horizons.
As official election returns finalize over the coming days and weeks, disciplined market participants will focus on tracking verified policy changes rather than reacting to short-term news headlines. By utilizing structured quantitative analytics and probability models from systems like SaPEX NEXUS's Geo Risk AI model, market participants can systematically separate genuine economic signals from transitory election-driven market noise, maintaining balanced portfolio exposure across volatile economic cycles.
1. SaPEX NEXUS Research Team. Internal analysis compiled Oct 27, 2026.
2. See our Methodology and Risk Disclosure pages for more on how these figures are derived. This article is for informational purposes only and does not constitute financial, legal, or investment advice.