Gaza Conflict Escalation Drives Market Risk Premium Across Key Global Sectors
Strategic Conflict Overview and Current Indicators
Data compiled yesterday, October 29, 2026, by the SaPEX NEXUS Geo Risk AI model assigned an 85 percent probability score and a critical severity rating to the ongoing situation in Gaza. Despite public discussions surrounding ceasefire initiatives, military strikes across the Gaza Strip have persisted, resulting in dozens of fatalities and a rapidly worsening humanitarian situation. The Gaza Health Ministry has issued urgent requests for the immediate opening of the Rafah crossing to enable the evacuation of severely injured individuals requiring critical medical treatment abroad.
The 85 percent probability metric generated by the SaPEX NEXUS Geo Risk AI engine reflects an elevated likelihood that regional friction will generate tangible cross-asset volatility rather than resolving through immediate diplomatic breakthroughs. In quantitative risk assessment, an 85 percent probability threshold signifies that analytical models anticipate ongoing operational disruption and market stress across affected geographic zones. When military developments coincide with severe humanitarian distress, financial markets historically build in structural risk premiums to hedge against unpredictable escalation scenarios.
The concurrent presence of active military engagement and diplomatic ceasefire assertions creates an environment of acute policy ambiguity for market participants. The SaPEX NEXUS Intelligence Network observes that during periods of heightened conflict where humanitarian calls for medical access like the Rafah requests remain unresolved, broad capital markets tend to discount early diplomatic claims until verifiable reductions in active operations occur. The persistence of strikes despite diplomatic commentary underscores the persistent fragility of regional stability.
Energy Markets and Supply Route Vulnerabilities
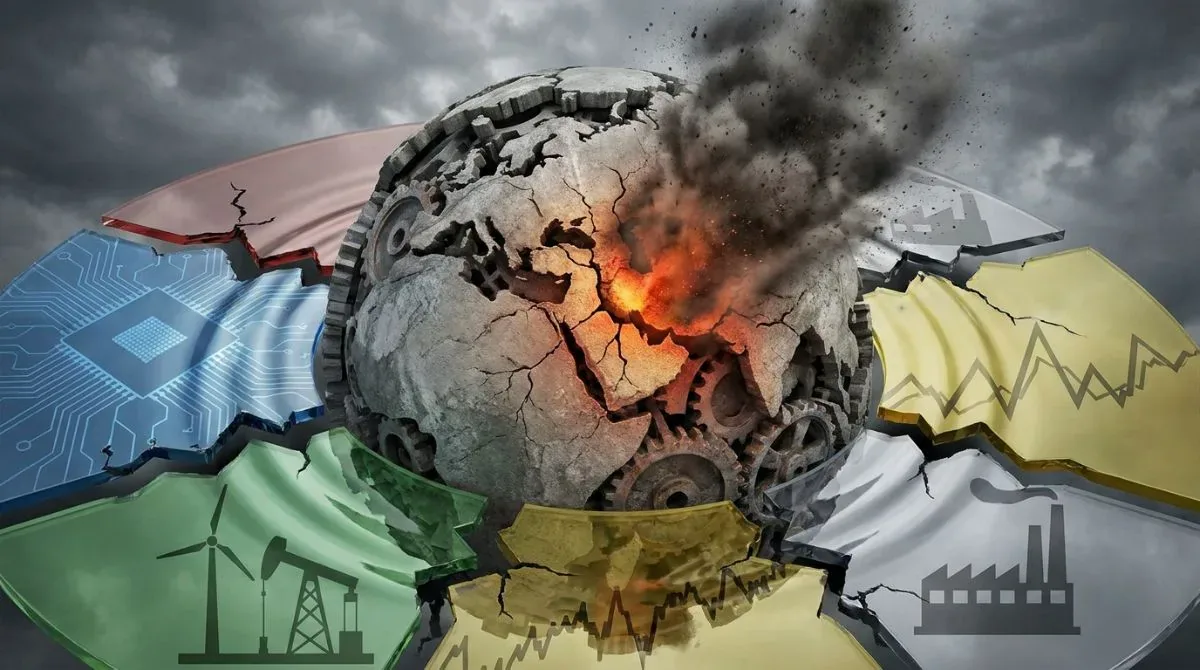
The SaPEX NEXUS Industry Impact matrix highlights five major economic sectors directly exposed to the unfolding crisis, specifically naming Energy, Shipping, Defense, Humanitarian Aid, and Insurance. Within energy markets, ongoing conflict near key regional transit corridors introduces persistent precautionary pricing across global crude benchmark contracts. The SaPEX NEXUS Geo Risk AI model indicates that while direct physical disruptions to oil production facilities remain probabilistic, the market perception of elevated vulnerability across Middle Eastern shipping channels inherently drives up crude futures premiums.
Shipping logistics across adjacent maritime routes face elevated operational costs due to rising war risk insurance rates. The SaPEX NEXUS Risk Assessment engine notes that insurance underwriters routinely re-evaluate premium tiers for commercial vessels operating within or near active conflict zones when overall event severity reaches critical status. Higher insurance premiums inevitably feed into broader freight costs, creating downstream price pressures across energy shipments and containerized trade passing through high risk regional routes.
Energy traders closely monitor whether regional tensions will spill over into broader supply chain disruptions. The SaPEX NEXUS Market Analytics platform records that sustained operational uncertainty leads commercial buyers to secure physical inventory in advance, reinforcing structural spot market premiums. While actual physical volume losses have not been explicitly calculated within the system, the continuous friction documented by the SaPEX NEXUS Geo Risk AI model maintains a constant upward floor under energy implied volatility metrics.
Safe Haven Flows and Regional Asset Pressures
In response to the critical severity assessment established by the SaPEX NEXUS Geo Risk AI model, global capital flows exhibit classical defensive positioning patterns across primary asset classes. Gold and the United States dollar have drawn sustained safe haven demand as institutional portfolio managers seek liquidity and capital preservation amid Middle Eastern instability. The SaPEX NEXUS Asset Sensitivity matrix tracks a clear correlation between elevated geopolitical risk metrics and increased demand for reserve currencies and bullion.
Conversely, regional equities and travel-dependent securities face clear headwinds as operational risks persist. The SaPEX NEXUS Intelligence Network identifies tourism-related stocks, regional banking equities, and local commercial enterprise indices as particularly vulnerable during sustained military operations. Prolonged instability reduces cross-border travel, delays capital expenditure plans, and depresses consumer confidence across neighboring commercial hubs.
The broader global market environment reflects a generalized increase in risk aversion, driven by systemic concerns over geopolitical contagion. According to the SaPEX NEXUS Market Analytics platform, high geopolitical risk premiums weigh on broader equity valuations by raising discount rates and increasing equity risk mandates. Until verifiable stabilizing events occur, institutional capital is expected to maintain a cautious distribution, favoring liquid defensive positions over speculative high beta assets.
Three to Six Month Economic Disruption Outlook
Looking toward a three month horizon, the SaPEX NEXUS Risk Horizon framework projects that continued military action and humanitarian stress will likely exacerbate broader regional tensions. This intermediate outlook highlights the high probability of persistent energy market volatility and localized economic disruption. The SaPEX NEXUS Strategic Analysis model indicates that sustained conflict over a ninety day period limits the effectiveness of short term diplomatic interventions, keeping supply chains and trade corridors under continuous strain.
Extending the horizon to six months, the SaPEX NEXUS Risk Horizon model assesses potential secondary systemic risks, including the destabilization of neighboring states and the potential involvement of additional regional actors. Over a six month timeframe, prolonged military engagement increases the likelihood of broader economic sanctions, unilateral trade restrictions, and retaliatory tariff measures imposed by global economic blocs seeking to exert diplomatic pressure.
These six month projections generated by the SaPEX NEXUS Macro Intelligence suite underscore how localized military events can evolve into wider macroeconomic friction points. When regional partners experience severe economic spillover, neighboring trade balances deteriorate, fiscal budgets are reallocated toward security needs, and regional trade corridors face recurring interruptions. Traders and enterprise risk managers must prepare for sustained structural friction across regional trade networks rather than expecting a rapid return to baseline conditions.
Twelve Month and Long Term Structural Realignment
Over a twelve month perspective, the SaPEX NEXUS Macro Intelligence suite projects that a protracted crisis could fundamentally alter regional political dynamics and institutional investment flows. Long term portfolio allocation models tracked by the SaPEX NEXUS Strategic Analysis system indicate that persistent risk in the Middle East prompts sovereign wealth funds and international institutional investors to recalibrate their emerging market exposures. Furthermore, sustained geopolitical tension over a one year horizon is projected to drive a lasting global increase in defense spending commitments.
The long term strategic outlook formulated by the SaPEX NEXUS Geo Risk AI framework suggests that multi-year instability induces fundamental realignments in regional alliances and global economic strategy. Persistent humanitarian challenges necessitate ongoing international financial aid allocations, while global energy consumers are forced to re-evaluate their long term energy security frameworks. Strategic planners increasingly prioritize supply chain redundancy, local energy transition initiatives, and diversified import channels to mitigate structural geopolitical vulnerability.
In summary, the 85 percent probability and critical severity metrics logged yesterday, October 29, 2026, by the SaPEX NEXUS Geo Risk AI model highlight a far reaching market environment where immediate humanitarian and military developments generate multi-layered financial repercussions. From short term safe haven surges in gold and the dollar to long term shifts in defense allocations and energy security planning, market participants must navigate a complex landscape defined by persistent geopolitical risk premiums.
1. SaPEX NEXUS Research Team. Internal analysis compiled Oct 30, 2026.
2. See our Methodology and Risk Disclosure pages for more on how these figures are derived. This article is for informational purposes only and does not constitute financial, legal, or investment advice.