UK Diesel Hits Record Highs as Middle East Conflict Escalates Risk
Energy Markets React to Escalating Middle East Hostilities
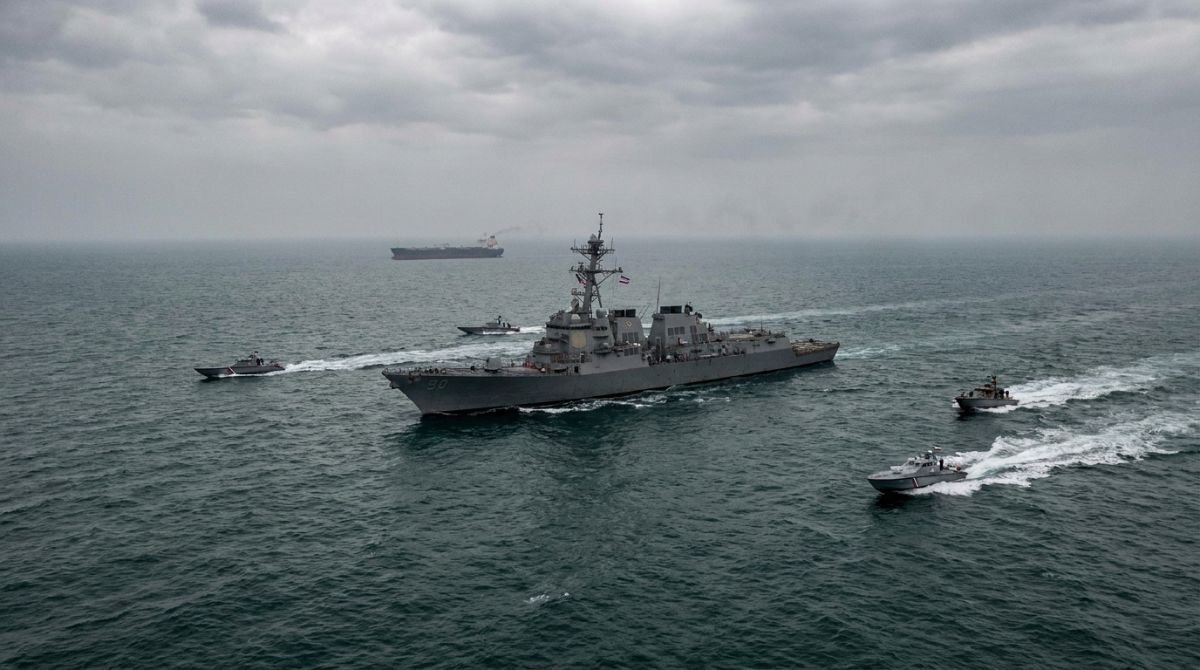
Two days ago, on September 28, 2026, intelligence feeds within the SaPEX NEXUS platform flagged a dramatic escalation in Middle East military hostilities involving the United States, Israel, and Iran. This development triggered an immediate reaction across international energy benchmarks, directly driving United Kingdom diesel prices to all time record highs. According to the SaPEX NEXUS Geo Risk AI engine, this event carries a critical severity designation alongside a 100 percent event probability score. The sudden spike in refined fuel costs reflects acute anxiety regarding maritime transit security and regional oil processing infrastructure.
When military conflict directly involves major regional powers, energy markets quickly price in worst case operational scenarios. Diesel serves as the primary fuel for commercial transport, freight networks, and heavy machinery across Europe. Therefore, a price shock in UK diesel acts as an immediate systemic drag on wider economic activity. Per SaPEX NEXUS real time tracking, energy traders have moved rapidly to hedge against potential disruptions in crude oil supply lines and refined product distribution channels.
The wider mechanism behind these price swings involves the complex interplay between crude oil extraction, refining bottlenecks, and regional shipping lanes. When geopolitical tensions escalate near critical transit points, maritime insurance premiums rise rapidly, adding direct overhead costs to every barrel transported. SaPEX NEXUS analytical models highlight that even before physical supply is cut, financial markets adjust pricing to reflect risk premiums, driving retail and wholesale fuel costs to historical peaks.
Immediate Cross Industry Disruptions and Asset Movements
The ripple effects of this conflict extend far beyond the immediate fuel pump. The SaPEX NEXUS sector monitoring matrix identifies seven core industries facing immediate, intense operational pressures, namely Oil and Energy, Shipping, Defense, Airlines, Insurance, Manufacturing, and Retail. According to SaPEX NEXUS equity tracking metrics, global equity markets face substantial downward pressure as rising input costs threaten corporate profit margins and squeeze consumer purchasing power. Higher transport costs directly reduce net earnings for manufacturers and retailers who cannot instantly pass price increases to end consumers.
Simultaneously, commodity benchmarks reflect severe upward movement. Data from the SaPEX NEXUS commodity analytics engine indicates that crude oil prices, including both Brent and West Texas Intermediate benchmarks, are undergoing dramatic upward surges. In parallel, global capital is seeking refuge in classical safe-haven assets. Per the SaPEX NEXUS capital flow monitor, gold is seeing robust buyer demand as institutional investors reallocate funds away from volatile equities and high yield corporate credit into lower risk physical stores of value.
Foreign exchange markets are similarly feeling the strain of these energy developments. According to SaPEX NEXUS currency impact metrics, the currencies of major energy-importing nations are weakening against reserve currencies. Nations dependent on foreign oil supplies face expanding trade deficits when energy costs soar, putting direct downward pressure on national currency valuations. This dynamic creates a secondary inflationary impulse, as imported goods become more expensive in local currency terms.
The Three to Six Month Economic Horizon
Looking forward over a three month timeframe, analytical models integrated into SaPEX NEXUS project a period defined by sustained energy costs, elevated inflation metrics, and ongoing friction across global supply chains. According to the SaPEX NEXUS economic forecasting framework, these combined factors are expected to trigger widespread downward revisions in global growth forecasts. As shipping lines adjust transit routes to avoid high risk zones, turnaround times for commercial cargo lengthen, driving up freight rates and delaying component deliveries for manufacturing plants worldwide.
Extending the lens to a six month outlook, the macroeconomic picture becomes increasingly challenging. According to SaPEX NEXUS macroeconomic projection models, a persistent inflationary environment driven by elevated fuel costs will complicate central bank policymaking. Monetary authorities who had previously planned interest rate reductions may be forced to pause or reverse course, keeping borrowing costs elevated for an extended duration.
This prolonged period of high interest rates, combined with elevated operational overhead, dramatically elevates the overall risk of a global economic downturn. Per the SaPEX NEXUS recession probability index, sustained fuel price pressure acts as an unyielding tax on consumer spending and business investment. When central banks maintain restrictive monetary stances to fight energy induced inflation, the probability of regional or global recessions escalates significantly over the medium term.
Year Long Structural Adjustments and Monetary Policy Shifts
On a twelve month horizon, the structural consequences of sustained military conflict and high energy prices become deeply embedded in global markets. SaPEX NEXUS long term threat assessment frameworks indicate that a full year of geopolitical instability around Middle East energy corridors typically leads to a prolonged period of economic deceleration. Businesses faced with volatile fuel overhead and high capital costs alter their capital expenditure strategies, opting for cash preservation over aggressive expansion.
This shift forces a fundamental re-evaluation of national security policies and commercial supply chain design. According to strategic planning insights from the SaPEX NEXUS intelligence suite, governments and multinational corporations respond to twelve month risk cycles by seeking structural redundancy. Companies begin shifting manufacturing footprints closer to domestic end markets, while sovereign entities prioritize strategic fuel reserves and localized supply security over cost efficiency.
Central banks also face severe structural dilemmas at the one year mark. According to SaPEX NEXUS central bank monitoring protocols, monetary policymakers must balance the cooling effect of high energy costs against sticky, supply side inflation. Traditional monetary tools are designed to manage demand, but when inflation is driven by physical supply constraints and military conflict, raising or holding interest rates high can deepen an economic contraction without immediately resolving the underlying fuel shortage.
Long Term Shifts in Trade, Energy, and Global Alliances
Beyond the immediate twelve month economic cycle, the long term ramifications of this conflict threaten to permanently reconfigure the global economic architecture. Per the SaPEX NEXUS long range structural model, extended military conflict between major regional powers accelerates permanent shifts in global energy trade routes. Trade flows that once relied on direct maritime routes may permanently bypass volatile maritime corridors, altering international logistics hubs and maritime trade volumes for decades to come.
In response to chronic energy insecurity, capital expenditure in alternative energy and localized generation infrastructure is projected to accelerate sharply. According to SaPEX NEXUS clean technology funding analytics, sustained record fuel prices act as a major catalyst for corporate and sovereign investments in renewable energy, battery storage, and nuclear power. Entities seek to insulate themselves permanently from future fossil fuel supply shocks and geopolitical leverage.
Finally, long term political alignments are likely to undergo significant restructuring. According to SaPEX NEXUS geopolitical risk models, multi year conflict cycles force energy-importing and energy-exporting nations into new trade agreements and strategic pacts. These evolving power dynamics reshape bilateral trade terms, sovereign debt relationships, and overall global market access, creating a complex new operating environment for global investors and corporate planners alike.
1. SaPEX NEXUS Research Team. Internal analysis compiled Sep 30, 2026.
2. See our Methodology and Risk Disclosure pages for more on how these figures are derived. This article is for informational purposes only and does not constitute financial, legal, or investment advice.